Blog
How to Find the Right Financing Option for Your Construction Equipment Purchase
July 16, 2026Every contractor eventually hits the same wall: you’ve found the right machine, but paying for it outright would tie up money you need for payroll, materials, or the next job. At Eagle Power & Equipment, Inc., financing conversations come up almost as often as equipment conversations, and the two are more connected than most buyers expect. The financing you choose affects your cash flow just as much as the machine affects your productivity.
Where Can I Finance Construction Equipment?
You’ve got three main routes: equipment dealerships, banks and credit unions, or lenders who specialize in commercial equipment financing. Dealer financing tends to win out for a simple reason. It puts the equipment, the financing, and the after-sale support in one place instead of splitting your purchase across separate companies.
That’s how we’ve built our financing process at Eagle Power & Equipment, Inc. We help you find terms that make sense for your business, backed by CASE and Kubota equipment and a team you’ll keep working with long after the loan is signed.
What Financing Structures Should You Actually Compare?
The structure matters more than the interest rate alone. Here’s how the common options break down:
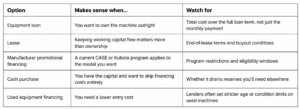
Once you’ve picked a structure, compare interest rate, down payment, repayment length, and monthly payment together, not one at a time. A low monthly payment stretched over a longer term can end up costing more overall than a shorter loan with a higher payment.
Why Do So Many Contractors Go With Dealer Financing?
Convenience is part of it, but it’s not the whole story. A dealer who sells and services the equipment already knows how it holds up, what it’s worth used, and which manufacturer programs are currently running. That’s harder to get from a bank loan officer who’s never seen the machine.
We can walk customers through current CASE and Kubota promotional rates when they apply, but we’re upfront that these programs change throughout the year. What’s available this quarter might not be there next quarter. We’ll confirm what’s actually live before you count on it.
How Does Financing Choice Affect The Business Beyond The Purchase?
This is where financing stops being a paperwork decision and starts being a business decision. A loan or lease that matches your equipment’s working life and the revenue it’ll generate keeps your budgeting realistic. One that doesn’t- say, a five-year loan on a machine you’ll want to trade in after two can leave you paying for equipment you no longer use.
We ask customers about their project pipeline before recommending a structure, because a business bidding on a single large job has different cash flow needs than one running a steady stream of smaller contracts.
Does The Dealer Matter After The Financing Is Approved?
Yes, and this is the part buyers sometimes overlook. The financing gets you the machine; the dealer determines what ownership actually feels like afterward. Parts availability, service turnaround, and technician expertise all shape your total cost of ownership just as much as your interest rate did.
At Eagle Power & Equipment, Inc., customers get factory-trained technicians, OEM parts, and service support alongside the financing. Not as a separate relationship, but as part of the same one.
What Should You Have Ready Before You Apply?
Applications move faster when you’re not scrambling for paperwork mid-process. Have these on hand:
- Business financial statements and recent tax returns
- Time in business and credit history
- Details on the specific machine, new or used
- Expected usage: hours per week, type of work
- Trade-in equipment information, if applicable
Accurate numbers upfront also mean we can point you toward financing that actually fits, instead of a generic plan that technically qualifies but doesn’t match how you’ll use the equipment.
Conclusion
The best financing option isn’t the one with the lowest advertised payment. It’s the one that matches how you’ll use the equipment and what your business can actually handle in cash flow. At Eagle Power & Equipment, Inc., we help contractors work through that comparison directly, backed by CASE and Kubota equipment, factory-trained service, and financing built around how the work actually gets done. If you’re ready to look at options, we’re ready to walk through what fits.
Frequently Asked Questions
Is financing better than paying cash for equipment?
It depends on what else that cash needs to cover. Plenty of contractors finance specifically to keep reserves available for payroll and materials, even when they could pay outright.
How long do financing terms typically run?
It varies by lender, equipment type, and borrower qualifications, so we won’t quote a standard number. Compare the total repayment period against the monthly payment for whatever term you’re offered, rather than assuming a default length.
Can used equipment be financed the same way as new?
Yes, though lenders often apply stricter limits based on the machine’s age and condition. Financing is available for both, but terms can differ.
What affects whether you get approved?
Business credit, time in business, financial documentation, and the equipment’s value all factor in. Stronger financial records generally open up better terms.
Where should I look if I want financing plus real equipment expertise?
Authorized dealerships tend to combine both in a way banks and independent lenders can’t. You’re getting financing from people who also know the equipment.

